In April 2026, the Ras Al Khaimah Tourism Development Authority (RAKTDA) confirmed that the number of UAE residents travelling to RAK increased by 93% year-on-year. This is more than just a statistic. It means that resort real estate in the northern emirate has, for the first time, gained a second sustainable demand engine — the domestic market. The UAE-Prop team analysed the data and observes that the investment model for Ras Al Khaimah is changing before our eyes.
Context
For decades, RAK developed as a destination for international tourism. In 2024, the emirate welcomed a record 1.28 million guests — up from 1.22 million in 2023. The strategic objective by 2030 is to triple international flow and double the number of hotels. The driver of this strategy is the opening of Wynn Al Marjan Island in the first quarter of 2027 — the first licensed casino in the Middle East.
But 2026 added an unexpected dimension. UAE residents — Emiratis and expats — began choosing RAK en masse as a staycation destination. The 93% YoY growth from the start of April is a figure that RAKTDA publicly attributes to a series of campaigns directed specifically at UAE residents: promoting beach resorts, cultural sites and outdoor activities within the emirate.
Why This Changes the Investment Math
Resort real estate in the UAE has historically operated on a single formula: yield = a function of international tourism. This formula imposed a rigid constraint — seasonality.
The high season peaks from November to March, when European, Russian and British tourists escape the winter. The trough runs from June to August, when temperatures climb above 45°C and foreign flow collapses. An owner-serviced apartment under this model achieved 65–70% occupancy and 7–9% net ROI.
Domestic flow rewrites this arithmetic. UAE residents travel year-round — on weekends, during school holidays, on national holidays. Their average spend is lower than international visitors, but their frequency is higher. And critically, they are active during the low season. This smooths out seasonality and offers the potential to lift net ROI to 9.5–10.5% on the same property.
What Works on the Investment Horizon
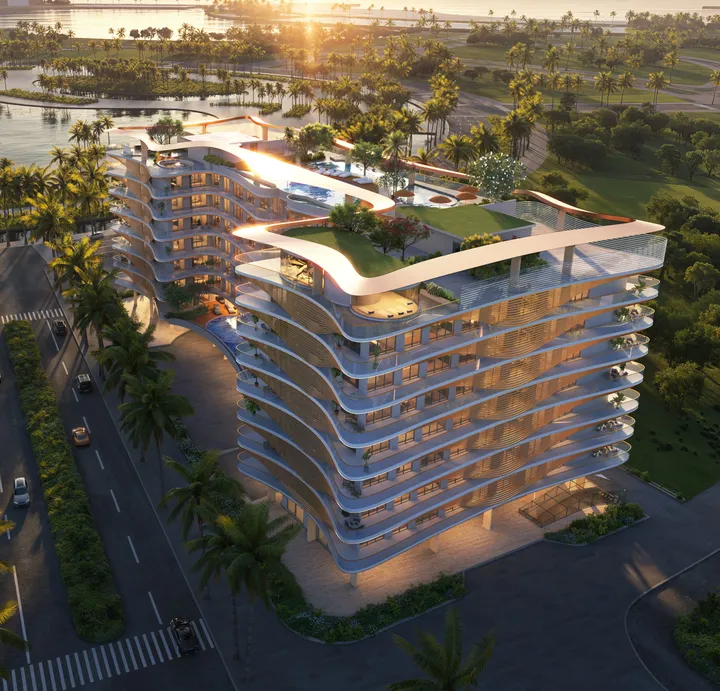
Al Marjan Island. This is the epicentre of change. Here you find Wynn, DoubleTree by Hilton, Rixos Bab Al Bahr and Mövenpick. This is where domestic demand concentrates — UAE residents head to a fully formed cluster, not to the coastline of a future development. Entry prices for a 1BR start from AED 950k, for a 2BR from AED 1.4M. Branded residences start from AED 1.6M.
Managed complexes with a rental pool. UAE residents book through RAKTDA-licensed platforms and management companies. An apartment outside a management structure loses up to 40% of potential domestic traffic. A lease-back with a rental pool is the recommended structure for new investors.
1BR–2BR format. Studios do not suit the family segment, which forms the core of domestic demand. Large villas are excessive for short staycations.
Entry timing — before Q1 2027. The opening of Wynn historically lifts capital values by 20–30% over a 12-month horizon. After that, the window for cheap entry closes.
Risks
The pipeline of new supply in RAK: 1.2k units in 2025, 1.3k in 2026, 1.9k in 2027, 5.2k in 2028. 2028 marks the peak of new completions. There is a high probability of temporary pressure on occupancy and rental rates. The financial model should include a scenario of cap rate compression in 2028 of 0.5–1 percentage point.
UAE GDP is growing 4.3% YoY (2025), with similar forward guidance. Domestic flow depends on the purchasing power of residents — should the economy slow, staycation demand will be the first to contract.
What We Recommend
Resort real estate in RAK is currently, structurally, one of the most compelling propositions on the UAE market. The entry price is one and a half to two times lower than Dubai Marina or JBR, while the yield, driven by the dual engine (international + domestic), is comparable or higher. The window is 12–18 months until the Wynn opening.
The UAE-Prop team works directly with RAK developers (Marjan, Al Hamra, RAK Properties). We help select a unit with a rental pool, verify RAKTDA licensing, and build a financial model that accounts for domestic flow. Get in touch for property selection in Q2 2026.
Sources: MICE Travel Advisor — Ras Al Khaimah 2026: Record Domestic Tourism Growth | RAKTDA Corporate | Gulf News
FAQ
What is the difference between the RAK and Dubai yield models?
Dubai operates on international tourism + business travel + long-term expat rentals. RAK operates on international tourism + domestic staycations. Domestic demand in Dubai is weaker because UAE residents travel to Dubai for work, not for leisure. RAK wins on the staycation format.
What is the average yield on a serviced apartment in RAK?
8–10% net ROI after management fees, OTA commissions and taxes. Factoring in domestic flow in 2026 — the potential is 9.5–10.5%.
What matters more — being close to Wynn or close to the beach?
The beach. Domestic tourists travel to RAK primarily for the beach. Wynn will be a driver for the premium segment (high spend, casino tourism) — a separate sub-market.
How does UAE-Prop assist investors in RAK?
Direct contacts with developers, due diligence on rental pools, financial modelling with double-engine demand, and legal support for the purchase. No intermediaries.
When is the optimal time to enter?
Within the next 12 months — before the opening of Wynn Al Marjan in Q1 2027. After that, entry costs will rise by 20–30%.