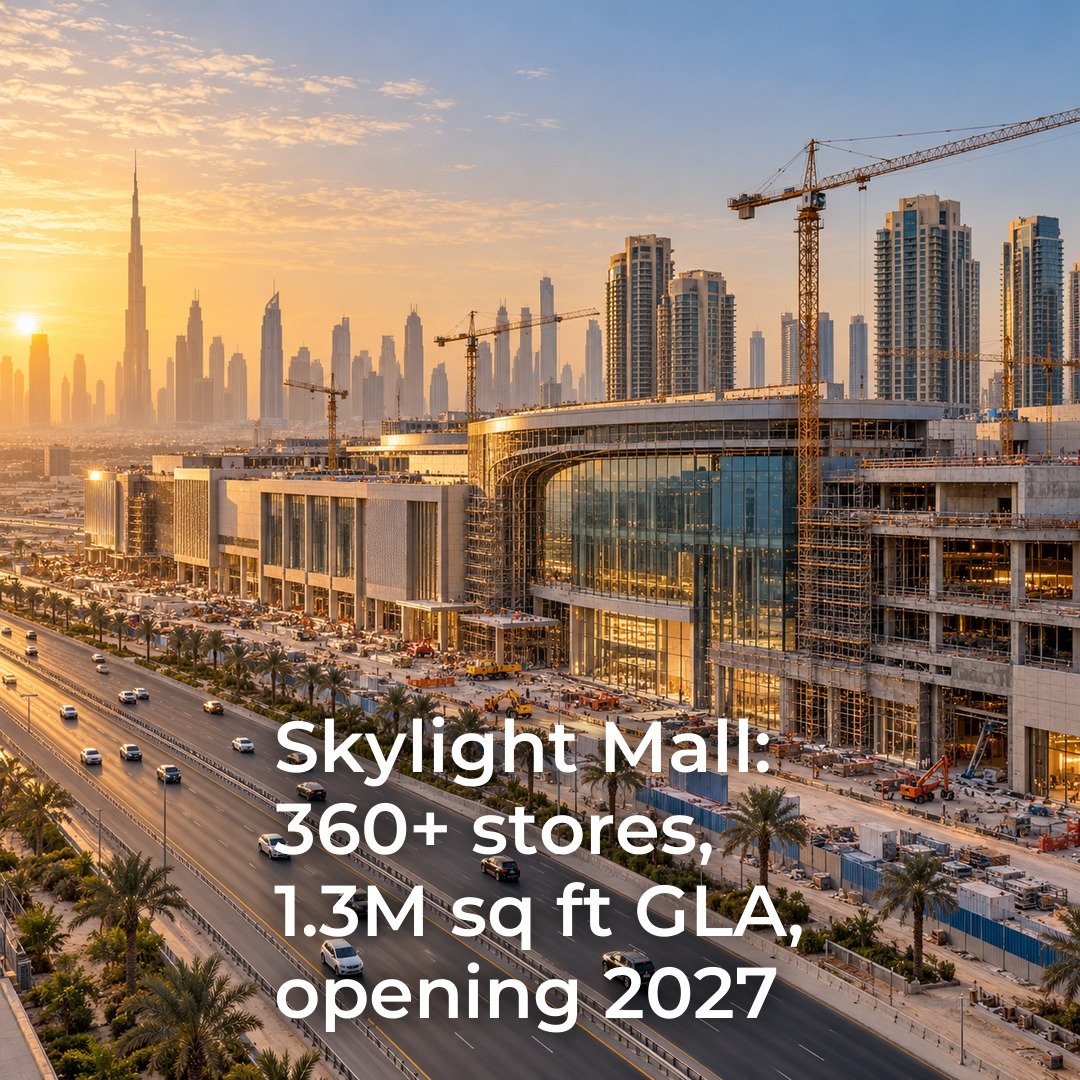
A new super-regional mall has been announced for Al Khail Road, with opening set for 2027. The operator, Dubai Retail, a unit of Dubai Holding Asset Management, presented Skylight Mall on 6 October 2026. It declares 1.3 million sq ft of gross leasable area and more than 360 stores. It also plans restaurants, entertainment and everyday services. The target catchment named by the operator covers Jumeirah Village Triangle, Jumeirah Islands, The Springs and neighboring communities.
For a buyer weighing a home in those areas, the announcement is useful context. It is not a price forecast. Our team reads it as a data point to be weighed against the rest of the file on a given property.
What the operator has actually confirmed
The list of confirmed facts is short. The opening year is 2027, and the exact month has not been published. The leasable area is 1.3 million sq ft. The store count is above 360. The operator says that with Skylight Mall its portfolio reaches 58 malls and lifestyle destinations across the emirate.
That last figure needs careful handling. The operator counts malls together with lifestyle destinations, so it should not be retold as 58 full-format malls. Buyers who repeat the number in conversations with sellers or other investors should keep the wording intact.
Brands have not been named. A store count describes planned capacity. It says nothing yet about which retailers will sign, how much of the space will be pre-leased, or what the mix between fashion, grocery, dining and entertainment will look like. A mall anchored by a strong supermarket and a cinema serves a neighborhood very differently from one anchored by luxury fashion, and the difference shows up in how often residents actually use it.
Reading the scale correctly
Gross leasable area is the floor space that can be rented to tenants. It is smaller than the total built area of the building, which also includes corridors, parking, back-of-house zones and service areas. When two projects are compared, the comparison only holds if both numbers use the same definition.
On published figures, Dubai Hills Mall is the bigger project. Its developer describes it at 2 million sq ft of leasable area and more than 650 stores. Skylight Mall at 1.3 million sq ft and 360 stores sits at roughly two thirds of the leasable area and a little over half of the store count of that benchmark. It is a large project, and still a step below the emirate's biggest destinations.
At the other end of the scale sits City Centre Me'aisem, which opened in 2015 with just over 53 outlets and a stated aim of serving more than 11 surrounding communities. Its operator positioned it as a daily-needs centre for nearby residents. Skylight Mall will land between these two reference points, and it would be a mistake to treat any of them as a direct stand-in for the others, because catchment size, road access and competing supply differ in each case.
Why a mall matters to a residential area
Residents rarely choose a district because of a mall alone. They choose it for the home, the school run, the commute and the price. A large retail centre changes the daily routine, though. Groceries, pharmacies, banking, restaurants, children's activities and weekend entertainment all sit within one short drive, which lowers the friction of living in a community that was originally planned around villas and townhouses with limited commercial space.
For owners, that convenience can support demand from end-users who value a complete neighborhood. It can also help with tenant retention, because renters who have everything nearby tend to stay longer. Those effects are plausible, and they develop slowly. Nothing in the announcement lets anyone assign them a percentage.
The market backdrop
The wider transaction picture calls for restraint. According to an analysis of Dubai Land Department data, off-plan sales made up 59% of the value of transactions in the third quarter of 2026, against 68% a year earlier. The quarter recorded around 37,400 transactions worth AED 92.9 billion. The mix is shifting, and the shift matters for anyone buying a unit that will be handed over after the mall opens.
When off-plan activity cools, buyers gain negotiating room and time to compare projects. They also face more competition from ready homes that can be inspected, rented and financed at once. A new piece of infrastructure does not cancel this. It becomes one of several factors in a district that is competing for the same pool of buyers as every other district.
What it means for off-plan buyers
For a buyer considering a project near Al Khail Road, the announcement raises the value of a few concrete checks.
Actual distance and route
The operator names communities, and it has not published drive times. A mall that sits on the same arterial road can still be a long journey if access points, interchanges and traffic patterns do not line up with the entrance to a particular community. Our team recommends driving the route at the times that matter, such as a weekday evening and a weekend afternoon, before giving the mall any weight in a purchase decision.
Timeline of the infrastructure
An opening year is a planning target. Construction schedules shift, and a project handing over in 2027 should be evaluated on the assumption that the mall may open later than announced. Buyers should look at what the property would offer on its own if the mall opened a year late.
Competing retail
Existing centres in the same belt already serve these communities. Their tenant mix, parking and renovation plans all affect how much of the new demand Skylight Mall can capture. A buyer who maps the competing supply within a 15 to 20 minute drive gets a more honest picture than one who reads only the announcement.
District planning and service charges
Master plans, school capacity, road upgrades and service charges all shape a community more than a single mall does. Nearby retail leaves a cheaper unit in a district with weak services unattractive, and a store count cannot justify an expensive unit's price.
The Golden Visa angle
Holders of the Golden Visa, and buyers planning to qualify for it, can reasonably treat the news as part of a long-term quality-of-life assessment. The announcement changes no visa criteria and creates no entitlement. Anyone relying on a property purchase for residency should work from current official requirements, which are documented separately and updated independently of retail news.
Investors looking across Dubai, Abu Dhabi and Ras Al Khaimah
Skylight Mall is a signal that capital continues to flow into Dubai's retail infrastructure, and that competition among retail destinations is intensifying. It is a poor indicator for Abu Dhabi or Ras Al Khaimah. Those markets run on their own population growth, tourism flows, rental yields and development pipelines, and a comparison between emirates needs data on each of those factors. A headline about a mall in Dubai supplies none of it.
Within Dubai, the better comparison looks beyond the number of stores. It looks at catchment size, transport links, the quality of anchor tenants and the supply of competing centres. Two malls with the same store count can generate very different footfall.
What we would watch next
Three pieces of information will tell buyers far more than the announcement did. The first is the tenant list, because named anchors reveal the positioning of the mall. The second is the confirmed opening date, because it converts a target into a schedule. The third is independent analysis of how comparable openings affected nearby residential prices and rents. At the moment, no such analysis has been published for this project, and the same caution applies to claims from any seller who promises a premium for proximity.
Until those pieces arrive, the sensible position is to treat Skylight Mall as a plus on the list of neighborhood amenities, weighted modestly, and to keep the weight of the purchase decision on the unit, the developer, the payment plan and the price per square foot compared with the surrounding market.
Frequently asked questions
When will Skylight Mall open?
The operator has announced 2027 as the opening year. The exact month has not been published, and buyers should treat the year as a planning target.
How big is Skylight Mall compared with Dubai Hills Mall?
The operator declares 1.3 million sq ft of leasable area and more than 360 stores. Dubai Hills Mall is described by its developer at 2 million sq ft and more than 650 stores, so Skylight Mall is the smaller of the two on published figures.
Will the mall raise property prices nearby?
No independent analysis supports a specific price effect. Proximity to retail can improve daily convenience and tenant appeal, but prices depend on supply, financing conditions, the quality of the community and the wider market cycle. Our team advises buyers to verify route, timeline and competing retail before attaching any premium to the announcement.
The parameters and timing described here rest on the operator's announcement of 6 October 2026. The tenant list, the exact opening date and independent analysis of the effect on residential prices have not been published in available sources.
If you are comparing homes around Al Khail Road, our team helps buyers evaluate the distance, the delivery schedule and the competing supply for each specific project.